A business can be profitable and still run short of cash.
It can also hold more cash than it reasonably needs, leaving capital sitting idle when it could be used for growth, debt reduction, distributions, or other strategic priorities.
That is why the question, “How much cash should our business keep in reserve?” rarely has a simple answer.
Rules of thumb can be useful as a starting point, but the right reserve depends on how the business actually operates.
A company with predictable recurring revenue, low debt, and limited capital requirements may need a very different cushion than a seasonal business with concentrated customers, significant payroll, and large working capital swings.
The goal is not to accumulate the largest possible bank balance.
The goal is to maintain enough liquidity to protect the business, support its strategy, and avoid making decisions under financial pressure.
- There is no universal cash reserve amount that is right for every business.
- Revenue predictability, fixed costs, working capital, debt, customer concentration, seasonality, and growth plans all influence reserve needs.
- Cash needed for normal operations should be considered separately from contingency reserves and strategic capital.
- Holding too little cash creates risk, but holding significantly more than the business needs can also have an opportunity cost.
- Forecasting is one of the most useful tools for determining how much liquidity a business actually requires.
Why Business Cash Reserves Matter
Cash reserves give a company time.
Time to respond when a customer pays late. Time to absorb an unexpected expense. Time to handle a downturn without immediately cutting staff or borrowing under pressure. Time to make an investment when an opportunity appears.
That flexibility has real strategic value.
Without adequate liquidity, even a profitable company can find itself making short-term decisions that damage the long-term business.
Management may delay hiring, postpone maintenance, draw on expensive credit, reduce marketing, or turn down opportunities simply because cash is unavailable at the wrong moment.
A reserve creates a buffer between an unexpected event and an emergency decision.
Why “Three to Six Months of Expenses” Is Too Simple
Business owners often hear that they should maintain three to six months of operating expenses in cash.
That can be a useful reference point. It should not automatically become the answer.
Two companies with $500,000 in monthly expenses can have completely different liquidity needs.
| Factor | More Predictable Business | Higher-Risk Business |
|---|---|---|
| Revenue | Recurring and diversified | Project-based or volatile |
| Customers | Broad customer base | Significant concentration |
| Collections | Predictable | Long or inconsistent |
| Seasonality | Limited | Significant |
| Debt | Low | High fixed debt service |
| Capital Needs | Modest | Equipment or inventory intensive |
| Forecast Visibility | Strong | Limited |
| Access to Credit | Reliable | Limited or uncertain |
Both companies may spend the same amount each month.
But the second business likely needs greater financial flexibility.
The appropriate reserve should therefore reflect the risk profile of the business, not simply a multiple of monthly expenses.
What Determines the Right Cash Reserve?
Several factors should influence how much cash a business keeps available.
Revenue Predictability
Businesses with recurring or contractual revenue generally have more visibility into future cash inflows.
Businesses relying on projects, transactions, discretionary spending, or irregular orders may experience much larger swings.
The less predictable revenue becomes, the more valuable liquidity can be.
Customer Concentration
If 30% or 40% of revenue comes from one customer, management should consider what happens if that customer reduces purchases, delays payment, or leaves entirely.
This connects directly to the broader issue of customer concentration risk.
A concentrated company may want more liquidity not because a customer loss is expected, but because the financial impact of one could be significant.
Fixed Costs
Some expenses disappear quickly when revenue declines. Others do not.
Payroll, rent, insurance, debt service, software contracts, and facility expenses may continue regardless of short-term sales performance.
The greater the fixed-cost base, the less flexibility management has during a downturn.
Working Capital Requirements
A profitable business can consume significant amounts of cash through working capital.
Growth may require additional accounts receivable, inventory, labor, materials, work in process, deposits, or prepaid expenses.
If customers pay in 60 days while payroll occurs every two weeks, the business may need to finance a substantial gap.
This is why cash reserves should be considered alongside working capital, not independently from it.
Seasonality
Seasonal businesses often accumulate cash during strong periods to fund weaker ones.
The important question is not simply the average monthly expense.
How low does cash normally get during the most demanding part of the annual cycle?
A twelve-month view can reveal liquidity needs that are easy to miss when management looks only at today's bank balance.
Debt Obligations
Debt creates fixed cash requirements.
Management should understand monthly principal and interest payments, covenant requirements, balloon payments, variable-rate exposure, equipment financing, and available borrowing capacity.
A business with significant leverage may need more liquidity because its obligations continue even when operating performance temporarily declines.
Capital Expenditures
Some companies can defer equipment purchases. Others cannot.
Manufacturers, contractors, transportation companies, medical businesses, and other capital-intensive organizations may face large expenditures necessary to maintain operations.
A reserve policy should recognize those foreseeable requirements.
Growth Plans
Growth often consumes cash before it produces cash.
A new location, additional employees, inventory expansion, equipment, marketing, or an acquisition may require investment months before the resulting revenue arrives.
That means management needs to distinguish between cash held for protection and cash intentionally accumulated for growth.
A Practical Cash Reserve Framework
Rather than treating every dollar in the bank as one pool of available cash, it can be helpful to think about liquidity in three layers:
Operating cash. Contingency reserves. Strategic cash.
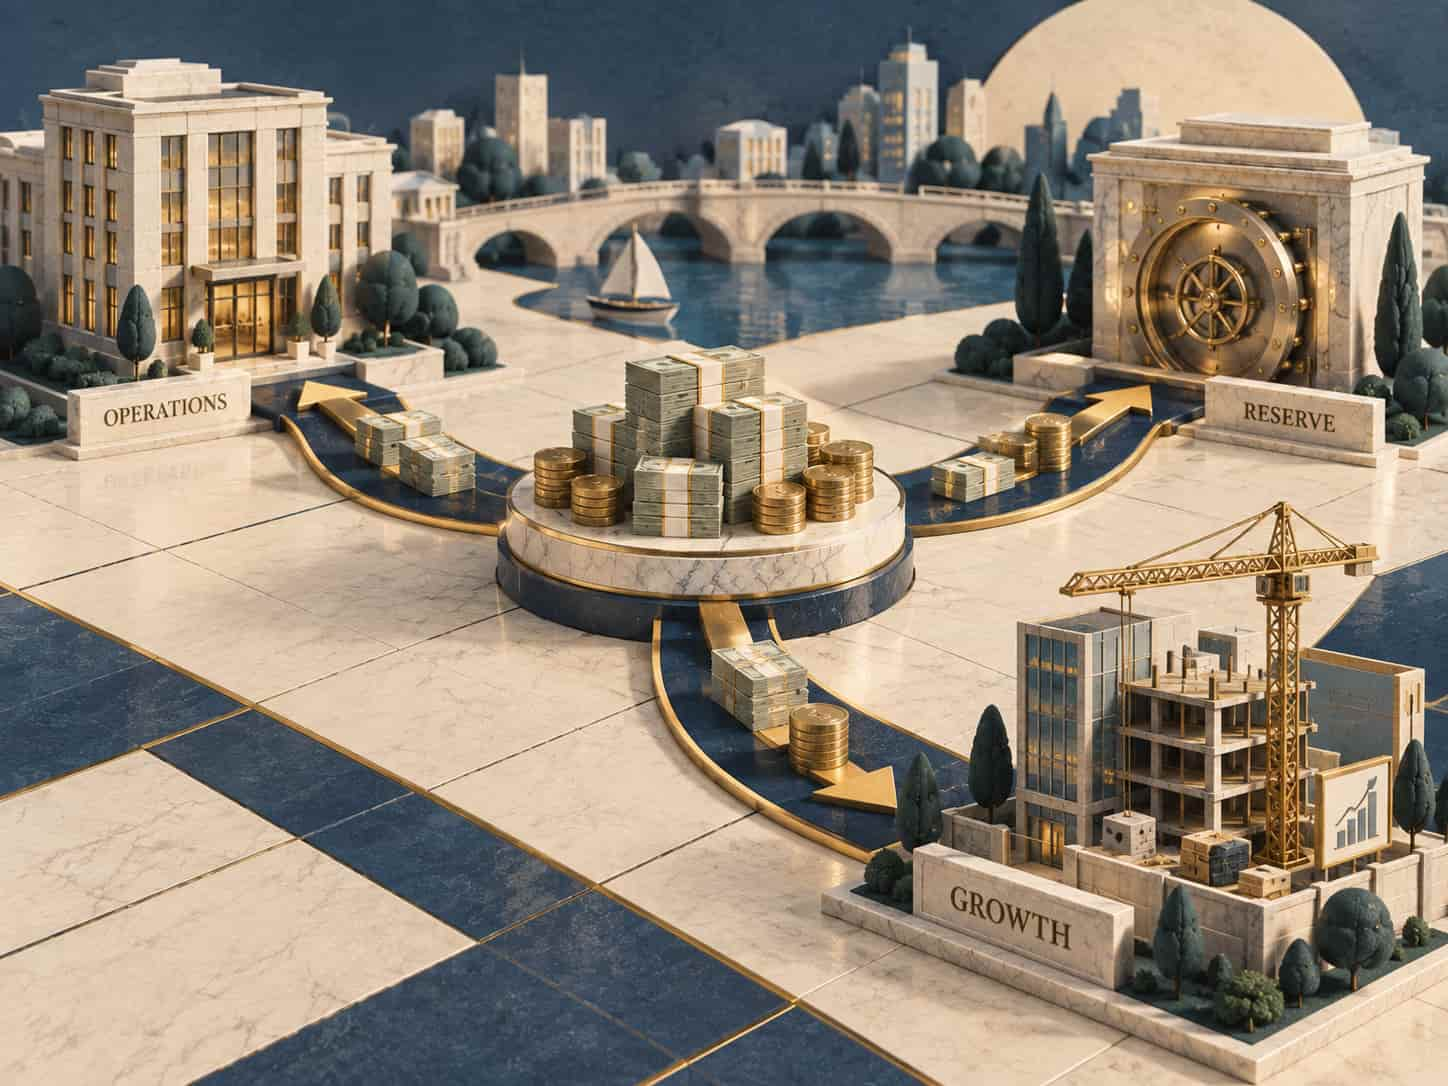
| Cash Layer | Purpose |
|---|---|
| Operating Cash | Supports normal payroll, vendors, taxes, debt payments, and routine business activity. |
| Contingency Reserve | Protects the business against unexpected revenue declines, delayed collections, or unplanned expenses. |
| Strategic Cash | Funds planned investments such as hiring, equipment, acquisitions, expansion, or other growth initiatives. |
This distinction matters.
A company may appear to have $2 million of cash, but if $1.2 million is needed to support normal operations and $500,000 is committed to an upcoming equipment purchase, the true contingency reserve is much smaller.
Simply looking at the bank balance does not answer the liquidity question.
Start With the Downside Scenario
One of the most practical ways to establish a reserve is to model what management actually worries about.
| Scenario | Assumption |
|---|---|
| Base Case | Revenue and collections continue according to plan. |
| Moderate Downside | Revenue declines 10% and collections begin to slow. |
| Severe Downside | A significant customer is lost and revenue declines 25% for several months. |
Then ask:
- How low does cash fall?
- When would the company need to borrow?
- Can payroll still be met comfortably?
- Can debt obligations still be serviced?
- Which costs can realistically be reduced?
- How quickly can management respond?
- How long would the business need to recover?
That analysis creates a much more useful reserve target than simply choosing a number because another company uses it.
Cash Reserve vs. Available Line of Credit
A revolving line of credit can provide useful liquidity.
But available borrowing and cash reserves are not identical.
Credit availability may change. A lender may tighten requirements during an economic downturn, exactly when the business needs liquidity most.
Borrowing also creates interest expense and additional leverage.
A strong liquidity strategy may include both cash and available credit, but management should understand what each source is expected to accomplish.
The existence of a credit line does not necessarily eliminate the need for cash reserves.
Can a Business Hold Too Much Cash?
Yes.
Cash provides safety and flexibility, but it also has an opportunity cost.
Once a business has sufficient liquidity for operations, risk, and near-term strategic plans, management should consider whether additional capital has a better use.
Potential alternatives may include:
- Paying down debt
- Investing in equipment or technology
- Hiring
- Expanding into new markets
- Acquiring another company
- Funding retirement plans
- Making owner distributions
- Improving facilities
- Investing in sales and marketing
The correct decision depends on the company's goals, expected returns, tax position, debt structure, and risk tolerance.
The point is not that excess cash should automatically be distributed.
It is that cash should have a purpose.
Operating Cash vs. Excess Cash
This distinction becomes particularly important in mature privately held businesses.
Owners may look at a large cash balance and assume all of it is available.
But management first needs to determine how much cash is required to operate the company safely.
Suppose a company has $3 million in cash.
- $1 million supports normal operating requirements
- $600,000 represents an appropriate contingency reserve
- $400,000 is needed for planned capital expenditures
That leaves approximately $1 million that may reasonably be considered excess relative to the company's identified needs.
At that point, management can make a strategic decision about how that capital should be deployed.
Without that analysis, the business is simply accumulating cash without knowing how much it truly needs.
The Role of Forecasting
This is where financial forecasting becomes critical.
A cash reserve should not be based only on what happened last year. Management needs to understand what is likely to happen next.
A useful forecast incorporates:
- Revenue expectations
- Customer collections
- Payroll
- Vendor payments
- Taxes
- Debt service
- Capital expenditures
- Hiring
- Distributions
- Working capital
- Planned investments
That creates visibility into the periods when the company is likely to generate cash and when it may consume it.
A rolling forecast can also help management update its reserve target as conditions change.
If a major customer is lost, liquidity needs may increase. If debt is repaid, reserve requirements may decrease. If the company is preparing for an acquisition, strategic cash requirements may rise significantly.
Cash reserve planning should be dynamic because the business itself is dynamic.
The Bigger Financial Picture
Cash reserves are a good example of why business decisions become stronger when accounting, forecasting, tax planning, and strategy work together.
Reliable financial reporting tells management where cash is today.
Working capital analysis explains where cash is tied up.
Forecasting shows where cash may be going.
Tax planning identifies upcoming obligations and opportunities.
Strategic planning determines what management wants the capital to accomplish.
Those disciplines should not operate independently.
The question is not simply how much cash the company has. It is whether that cash is aligned with what the business needs and where the business is going.
Through Client Accounting & Advisory Services (CAAS), businesses can create the reliable financial reporting and visibility needed to understand cash, working capital, and operating performance.
That foundation can then support more forward-looking Financial Planning & Analysis (FP&A), including cash flow forecasting, scenario planning, budgeting, and strategic capital decisions.
Questions Business Owners Should Be Asking
- What is our minimum comfortable operating cash balance?
- How predictable are our monthly cash inflows?
- What happens if revenue declines 10%, 20%, or 30%?
- How much cash is tied up in receivables and inventory?
- How concentrated is our customer base?
- What fixed expenses cannot be reduced quickly?
- What debt payments must be made regardless of performance?
- What capital expenditures are likely over the next 12 to 24 months?
- What cash will our growth strategy require?
- How much unused credit is available?
- What upcoming tax obligations should be considered?
- How much of our current cash balance is truly excess?
Those questions provide a much stronger foundation than simply asking how many months of expenses should be sitting in the bank.
Build Liquidity With a Purpose
Strong liquidity does not mean maximizing cash at all costs.
It means having the financial flexibility to handle uncertainty while still putting capital to productive use.
For some companies, that may require a substantial reserve.
For others, predictable revenue, low leverage, strong working capital, and reliable access to credit may allow management to operate comfortably with less.
The appropriate amount changes as the business changes.
That is why the strongest approach combines financial reporting with forecasting, scenario planning, working capital analysis, tax strategy, and capital planning.
Because the goal is not simply to have cash.
It is to have the right amount of cash available when the business needs it most.
Turn Cash Visibility Into Better Decisions
Understanding how much cash your business needs can help management prepare for uncertainty, fund growth, and make more confident decisions about capital.